
You convert 80% of fintech app users during onboarding by reducing uncertainty faster than you add friction, and by sequencing KYC so it feels like a fair trade for access, limits, or speed. The psychology is simple: when money is involved, users default to caution, your job is to create trust, momentum, and error-proof execution in the first session.
This guide breaks onboarding into the moments that actually drive completion: the trust decision, the “do I keep going?” decision, and the “did it work?” decision. The sections follow real questions teams ask when KYC, identity checks, and performance issues start crushing conversion. You’ll get practical patterns, copy moves, and experiment ideas that lift completion without weakening risk controls.
Why Do Fintech Users Abandon Onboarding So Often, Especially At KYC?
Fintech onboarding fails where users feel high risk and low control. The risk is emotional before it’s rational: personal data, identity documents, and the fear of being trapped in a “review” state with no clear end. Once that fear shows up, users stop investing effort, and every extra step reads as a warning sign rather than a requirement.
Organizations report abandonment is widespread during digital onboarding, and identity proofing repeatedly shows up as a leading dropout driver alongside “the process is too long” and “too many manual steps.” Those categories map directly to what users experience as uncertainty and wasted time, not “compliance.” When your flow feels long, fragile, or bureaucratic, users protect themselves by exiting.
Consumer behavior aligns with that pattern: large numbers of people abandon enrollment when friction rises, and mobile-first behavior amplifies the effect. On a phone, a single confusing screen, a camera capture failure, or a timeout is enough to trigger drop-off. If the app also feels heavy or slow, users interpret performance as reliability, and reliability is non-negotiable when the product touches money.
What Does “80% Onboarding Conversion” Actually Mean For A Fintech App?
“80% conversion” only matters after the milestone is defined. In fintech, teams often mix four different endpoints: account created, KYC started, KYC approved, and first value event (funding, first payment, first trade, first transfer). Those are different products psychologically, since the user’s perceived commitment and perceived risk change at each step.
If the goal is executive-grade clarity, define conversion as a single event with a timestamp and a user state. A strong default is “reached a usable state within the first session”, then measure the follow-on conversions separately. That usable state might be limited mode, verified email and phone, linked bank pending, or partial KYC completed, depending on your risk model and what you can legally allow.
When teams claim “80% onboarding conversion” credibly, they usually mean 80% complete the next best step that leads to early value. That step must be observable, repeatable, and tied to a user benefit. If the metric is “KYC passed,” then the product needs to treat KYC as a core experience, not a compliance form, with instrumentation, recovery paths, and user messaging built like any revenue-critical funnel.
How Do You Reduce KYC Drop-Off Without Increasing Fraud And Compliance Risk?
KYC drop-off drops when the flow stops punishing normal users for normal failure modes. Most “bad UX” in verification is really unhandled exceptions: blurry images, glare, low light, name formatting mismatches, address normalization issues, document types the system barely supports, or a soft match that silently routes to manual review. If the happy path is smooth but the failure path is opaque, you don’t have a working flow, you have a demo.
Start by turning KYC into a measurable product surface. Track completion rate, step-level abandon, average time per step, retake rate for document capture, error categories, and manual-review turnaround. Then connect those metrics to user messaging, because users tolerate checks when they understand what is happening and what they should do next.
Risk does not require mystery. Users comply more when they see why you need something, what you will do with it, and how long it takes. If a review is needed, show the status, show the expected time window, and show what remains available while waiting. Many teams also win by offering an immediate fallback: “Verify in-app,” “Verify in a secure browser,” or “Continue with limited access,” while keeping controls intact until verification is complete.
Where Should You Place KYC In Onboarding: Upfront, Progressive, Or After Value Is Shown?
Placement is a sequencing decision, not a moral one. Upfront KYC can work when the user’s intent is already high and the payoff is immediate, like a product that cannot function at all without verification. It also works when the brand is already trusted and the user expects a bank-like experience. If neither is true, forcing full KYC on screen two often turns curiosity into suspicion.
Progressive onboarding usually converts better because it earns commitment before demanding documents. You let the user get oriented, see the product, set preferences, and understand the benefit of completing verification. Then KYC becomes an unlock tied to a specific capability: higher limits, instant transfers, investing access, faster payouts, or account recovery protection.
A practical model is tiered access. Gate what you must, then stage the rest at the moment the user requests power features. Keep the language direct: “To increase your daily transfer limit, verify identity.” That phrasing reads as a fair exchange and reduces the “why are you asking me this?” reaction that kills momentum.
What Psychological Principles Increase Onboarding Completion In Finance?
Fintech onboarding is behavior change under perceived risk. The principles that move completion are trust signaling, uncertainty reduction, progress, and competence. Users keep going when they feel they are doing the right thing, they are close to done, and the product is competent enough to safeguard sensitive activity.
Trust signaling is not decorative. It shows up in plain language, consistent UI, stable performance, clear policies, and visible control points: edit buttons, back navigation that doesn’t wipe progress, save-and-resume, and human support when automation fails. Trust also shows up when the product explains sensitive requests without sounding defensive or vague.
Progress is the engine of completion. Users push through friction when they can see it ending. That’s why checklists, progress indicators, and small wins lift activation across many products, and the mechanism transfers into fintech: a visible plan reduces overwhelm, and a completed step increases follow-through. Pair that with competence signals, fast validation, and predictable outcomes, and onboarding starts feeling safe rather than risky.
What Are The Biggest UX Trust Killers In Fintech Onboarding?
The fastest way to lose a user is to make the flow feel unreliable. “Processing…” with no time range, session timeouts that force restarts, broken deep links from email, and camera capture loops signal that the product cannot handle edge cases. In a money product, unreliability reads as danger, not inconvenience.
Another trust killer is language that feels like it was written for internal policy rather than users. “Identity proofing and affirmation” is fine in a report, not in an app screen. Users want to know what they must do, what it unlocks, and what happens if the system can’t verify them automatically. If the answer is “contact support,” users expect that before they hand over documents, not after.
Performance is a trust killer in disguise. Teams have reported KYC SDK bloat and long integrations that correlate with verification drop-off, which makes sense: slower load, larger app size, and heavier flows increase abandonment on mobile. When the app behaves like it’s struggling, users assume your systems will struggle with their money, and they exit before they regret it.
What Practical Experiments Lift Onboarding Conversion Fast In A Fintech App?
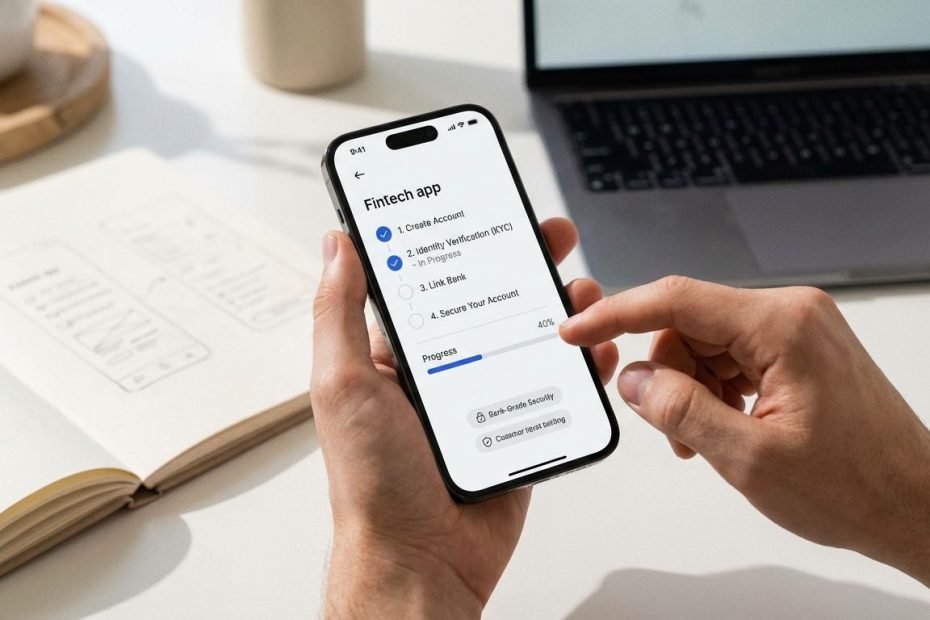
Run experiments that remove confusion first, then experiments that reduce effort. Confusion is more lethal than effort, since users interpret confusion as a hidden risk. Start with a single-screen onboarding plan: a short checklist of the minimum steps to reach first value, always visible, with deep links that drop users into the exact screen where the task is completed.
Real-world product teams have reported large activation gains from simple checklists and progress indicators, with shorter time-to-activation when users can see the path and finish it in fewer sessions. The key is not decoration, it’s clarity: “Do these five things, you’ll be ready.” In fintech, that can be “confirm email,” “secure account,” “link funding source,” “set passcode/biometrics,” “complete verification to unlock limits.”
Then fix form failure. Baymard’s testing shows many sites still fail inline validation basics, and users lose time when errors only appear on submit. Fintech onboarding is form-heavy, so implement live inline validation that avoids premature warnings, clears errors once corrected, and uses positive signals when inputs are accepted. Add recovery messaging for the top KYC failures, and measure retake rate and completion time before and after, that’s where fast conversion wins show up.
How Do You Design KYC Messaging That Feels Like Trust, Not Surveillance?
Users do not resist verification itself as much as they resist unclear motive and unclear outcome. Keep messaging specific and user-benefit oriented. Replace “We need this for compliance” with “Verify identity to protect your account and unlock transfers.” Avoid long text blocks, and avoid vague promises. Users want a predictable sequence, not reassurance.
Explain requirements right before they matter. If the next screen requests a driver’s license, say so on the prior screen and give quick capture requirements: lighting, glare, full frame, no blur. Users hate discovering rules after failing. When a user fails, show a direct reason and an immediate fix, not a generic error code or a loop back to the beginning.
If manual review exists, treat it as a product state with real UX. Show “Under review,” provide a time window, and provide a notification promise with opt-in. Also show what is available while waiting, even if it is limited. A silent queue converts uncertainty into churn, and churn is usually permanent at this stage.
How To Improve Fintech Onboarding Conversion
- Show a 3–5 step plan, keep it visible, deep-link every step.
- Use progressive KYC tied to limits, show time estimates and status.
- Add inline validation, strong error recovery, save-and-resume.
Build An Onboarding That Users Finish And Trust
Onboarding conversion in fintech is earned by making sensitive steps feel controlled, predictable, and worth it. Define “conversion” as a specific milestone, then instrument every step so friction becomes visible and fixable. Sequence KYC as an unlock when possible, and when it must be upfront, remove uncertainty with clear requirements, transparent status, and strong recovery paths. Treat performance as a trust feature, not a technical detail, and push hard on inline validation and exception handling since mobile users make small mistakes that should never become a dead end. When the product makes progress obvious and failure recoverable, 80% completion stops sounding like a marketing claim and starts becoming a repeatable outcome.
If tighter onboarding metrics, experiment plans, and KYC UX teardown notes are useful, visit linkedin profile for more fintech onboarding and conversion playbooks.
References
- ABBYY report coverage: “90% of companies lose potential customers during the digital onboarding process” (Business Wire): https://www.businesswire.com/news/home/20221115005637/en/90-of-companies-lose-potential-customers-during-the-digital-onboarding-process-according-to-ABBYY-State-of-Intelligent-Automation-Report-Q4-2022
- Inline form validation usability findings (Baymard): https://baymard.com/blog/inline-form-validation
- US consumers abandoning enrollment due to friction (The Paypers): https://thepaypers.com/payments/news/83-mln-us-consumers-abandon-online-enrollment-due-to-friction
- Practitioner thread on KYC integration time, SDK bloat, and drop-off (Reddit): https://www.reddit.com/r/fintech/comments/1r50w2u/kyc_integration_is_taking_3_months_and_our_mobile/
- Practitioner thread on onboarding and KYC drop-offs (Reddit): https://www.reddit.com/r/fintech/comments/1krtu63/i_learned_this_the_hard_way_but_apps_lose_users/
- Practitioner thread on keeping KYC UX intact (Reddit): https://www.reddit.com/r/fintechdev/comments/1o6eirx/how_do_you_handle_kyc_verification_flow_without/
- Checklist activation lift case (Reddit): https://www.reddit.com/r/SaaS/comments/1pkyskd/added_an_onboarding_checklist_to_the_product/