
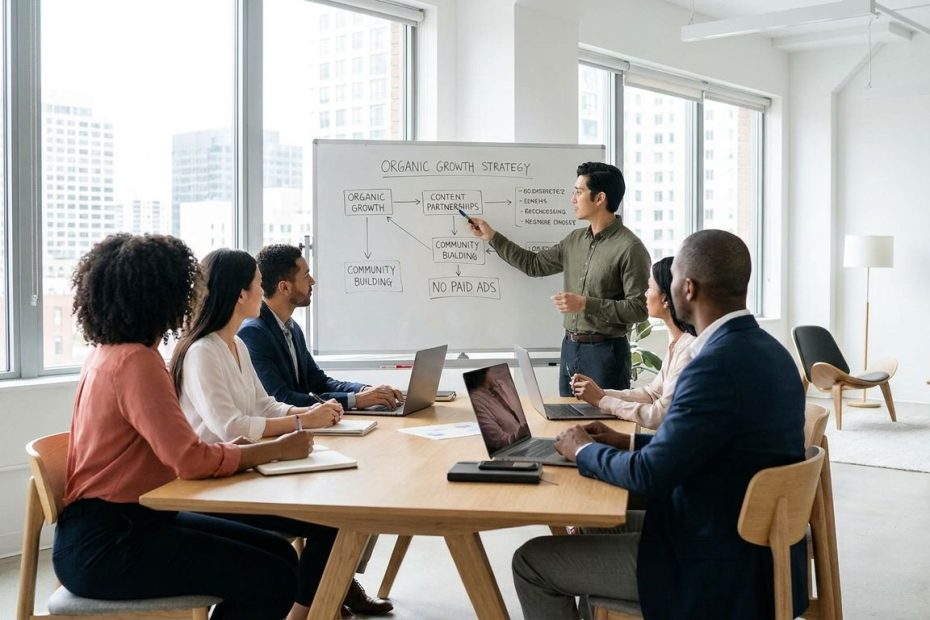
A fintech go-to-market strategy can get your first 10,000 users without paid ads by turning trust, product value, referrals, content, and partnerships into repeatable distribution. Your job is to make the product easy to believe, easy to share, and useful before a user ever sees a signup form.
For a new financial technology product, paid traffic can create signups before you know whether people trust the offer, understand the value, or stay after onboarding. This article gives you a practical path for organic user acquisition in fintech, using product-led growth, waitlists, education, referrals, community, and partner distribution. You’ll see how early-stage teams can move from “nobody knows us” to a credible first user base without relying on ad spend.
Why Paid Ads Often Fail For Early-Stage Fintechs
Paid ads can expose your product to a lot of people, but exposure isn’t the same as trust. In fintech, users are not just downloading another app; they’re being asked to connect bank accounts, share personal information, move money, or change a financial habit. That raises the bar for belief. If your product, onboarding, and trust signals aren’t ready, paid traffic can turn into expensive drop-off.
Early-stage fintech teams also face a different purchase path than many consumer apps. A user may read reviews, compare fees, check security language, ask a friend, and revisit your site several times before signing up. A paid click rarely solves all of that. Organic channels work better when they answer the user’s doubts before asking for commitment.
The better early move is to build demand around a clear financial pain. That could be cheaper international transfers, easier budgeting, faster business payments, better spending controls, or simpler investing education. When the pain is plain and the product removes friction, users have a reason to talk about it. That is where a no-paid-ads fintech go-to-market strategy starts to compound.
The Organic User Acquisition Mindset: Trust Over Transactions
Organic user acquisition in fintech starts with a simple rule: people share financial products only when the perceived benefit beats the perceived risk. A free account, lower fee, useful calculator, cleaner interface, or faster setup can get attention. Trust turns that attention into action. Without trust, even a clever referral loop will stall.
Trust has several visible parts. You need plain-language pricing, transparent policies, clean onboarding, recognizable partners where applicable, support access, educational resources, user reviews, and a product that behaves predictably. Don’t bury the details users care about. If users need to search for fees, limits, identity check requirements, or safety information, you’re adding doubt at the worst moment.
This mindset also changes how you measure growth. You don’t only count signups. You measure activated users, referred users, completed onboarding, repeat use, and support questions that signal confusion. A fintech company can reach 10,000 signups and still have a weak go-to-market motion if most users never complete the first meaningful action.
Step 1: Build A Product Worth Sharing
Product-led growth in fintech begins with a product promise that users can explain in one sentence. If users need a long pitch to describe why the app matters, referrals become hard. The strongest early products solve a narrow problem well before expanding into more features. That narrow wedge gives early users a reason to remember you.
Your first growth loop should be connected to real product value. If you offer spending alerts, the loop may come from shared household budgeting. If you offer business payments, it may come from inviting vendors, accountants, or team members. If you offer cross-border money movement, the loop may come from users telling people who face the same fee pain.
Before scaling distribution, review onboarding like a user with no patience. Ask whether the value appears before the hardest step. Ask whether identity checks are explained before they interrupt the flow. Ask whether users know what happens after signup. Organic acquisition gets easier when the product reduces uncertainty instead of creating more of it.
Step 2: Use A Waitlist With Viral Referral Mechanics
A waitlist can turn early demand into social proof when it gives users a reason to invite others. The best version is simple: join the list, invite friends, move up, unlock access, or receive a reward tied to the product. This works because it converts curiosity into a visible progression. Users don’t feel like they’re waiting in a black box.
Revolut and Monzo showed how strong waitlist and referral mechanics can support early growth. Revolut was reported to have grown with a zero-dollar customer acquisition cost through word-of-mouth and a waitlist referral system. Monzo’s Golden Ticket campaign gave users a shareable way to invite others into the product, turning access into a conversation starter.
Your waitlist should avoid gimmicks that don’t match the financial product. Don’t offer rewards that attract users who will churn after claiming the prize. Tie the incentive to the behavior you need: completed onboarding, first funded account, first transfer, first card use, first budget created, or first business invoice sent. Reward quality activation, not empty signups.
Step 3: Create Content That Answers Money Questions
Content marketing for banking apps and fintech products works best when it answers the questions users already ask before they trust you. People search for fees, comparisons, financial definitions, tax-related basics, budgeting methods, money transfer options, account setup steps, and risk explanations. If your content gives clear answers, it can bring qualified users before they’re ready to choose a provider.
Search engine optimization should not be treated as a blog calendar only. Build content around decision points. A useful calculator, comparison page, glossary, checklist, explainer, or product walkthrough can convert better than a generic article. Financial literacy content can also reduce support volume by explaining terms that users would otherwise ask your team to clarify.
Good fintech content needs precision. Avoid broad claims that sound like advertising. Use plain explanations, show the calculation method, state assumptions, and guide the reader toward the next useful action. A user who learns something valuable from you has already experienced part of your product promise.
Step 4: Build Strategic Distribution Partnerships
Partnerships can help a fintech startup reach users who already trust another platform, community, employer, marketplace, or service provider. The right partner has your target user’s attention at the moment your product is useful. That timing matters. A budgeting app promoted inside a financial education community has a clearer path than the same app posted randomly on social media.
Look for non-competing partners with shared user needs. A payroll platform may be relevant for earned wage tools. An accounting firm may fit a small-business finance product. A creator education platform may fit a freelancer banking product. A remittance product may fit community organizations that support international workers.
Keep the partner offer simple. Give partners a clear user benefit, co-branded education, easy tracking, and a low-friction handoff. Don’t ask for a broad launch before testing a smaller segment. One focused partner channel that activates users can beat ten loose partnerships that only produce logo placement.
Step 5: Grow Community And Word-Of-Mouth
Community-led growth works in fintech when the community has a real reason to gather. People do not join a financial product community just because a brand asks them to. They join because they want to solve a money problem, compare options, learn from peers, or influence a product that affects their financial routine. That makes listening as useful as publishing.
N26’s early growth was reported to rely on organic social media, community events, and a transparent brand, rather than paid marketing spend. That lesson matters for newer fintech teams. A community can create trust faster when founders, product leaders, and support teams respond with clarity. Silent brands struggle to earn word-of-mouth in financial services.
Use community channels to remove doubts, not to push constant promotions. Share product updates, answer onboarding questions, gather feature requests, and explain tradeoffs in plain language. When users feel heard, they’re more willing to invite others. Community also helps you detect the wording users use, which can improve your landing pages, content, referral copy, and support materials.
Step 6: Turn Social Proof Into A Trust Asset
User-generated content can help a new fintech earn credibility, but it needs guardrails. Financial products are personal, so users may not want to share screenshots, balances, account details, or private goals. Give them safer ways to advocate. They can share a referral link, review the app, describe a saved fee, mention a workflow improvement, or explain why onboarding was easy.
Social proof should be specific enough to be useful without exposing private information. “Saved time reconciling payments” is stronger than “great app.” “Set up a business account in minutes” is stronger than “love it.” You can collect feedback after a meaningful product moment, then request permission to use the comment in a landing page, email, or app store listing.
Review quality matters. Early users often look for signs that real people use the product and get support when something goes wrong. Make sure your support response quality matches your acquisition push. A referral program can bring users in, but visible frustration can slow the same loop down.
Step 7: Reduce Onboarding Friction Without Weakening Trust
Identity checks, risk reviews, account verification, and anti-money laundering controls can create friction in fintech onboarding. You can’t remove required steps just to improve conversion. You can explain them better, place them at the right moment, and show users what to expect. That alone can reduce abandonment.
Break the signup flow into understandable stages. Tell users why information is needed, how long a step usually takes, what documents may be required, and what happens after submission. If the product has limited access before verification, say so upfront. Surprise is one of the fastest ways to lose a financial user.
You should also separate curiosity from commitment. Let users explore pricing, benefits, educational tools, calculators, or demos before the deepest onboarding step. This gives users a reason to continue. It also makes your organic channels work harder because a visitor can receive value before making a trust-heavy decision.
Case Study Breakdowns: Revolut, N26, And Monzo
Revolut is a useful example because its early growth was tied to a clear user pain: spending and transferring money across borders with fewer headaches. Reports noted that it reached millions of users with zero customer acquisition cost, supported by word-of-mouth and referral-led waitlist mechanics. The lesson is not that every fintech can copy the same tactic. The lesson is that a strong wedge plus social sharing can lower dependence on paid media.
N26 offers a different lesson. Its early customer base was reportedly built without paid marketing, using community, organic social media, events, and a clear brand. That matters because banking products require a level of credibility that ads alone rarely create. A transparent brand can become a distribution channel when users repeat the message for you.
Monzo’s Golden Ticket campaign shows how access can become shareable without feeling forced. Users could invite others into the product, which made referrals feel like a benefit rather than a sales pitch. This type of mechanic works when the invited user understands the product value right away. If the invitation leads to a confusing signup path, the loop breaks.
Measure What Matters In Your Organic Growth Dashboard
Your dashboard should separate reach, trust, activation, referral, and retention. Reach tells you whether people are finding you through search, community, partners, social, app stores, and direct visits. Trust signals tell you whether people read pricing pages, safety pages, reviews, frequently asked questions, and comparison content. Activation tells you whether they complete the first meaningful product action.
Track referral rate, invite acceptance rate, waitlist conversion, content-to-signup conversion, partner channel conversion, onboarding completion, and first-week usage. These numbers tell you whether your organic user acquisition fintech motion is growing through real value. A spike in signups is less useful if users don’t complete onboarding. A smaller channel can be worth more if it brings users who activate and refer.
Measure support questions too. Repeated questions can reveal landing page gaps, unclear onboarding, confusing pricing, or weak product positioning. Treat those questions as conversion research. Fixing one unclear step can improve every organic channel at once.
Common Pitfalls That Slow Organic Fintech Growth
The first pitfall is launching a referral program before users have a reason to refer. Incentives cannot hide a weak product promise. If users don’t trust the product, understand the benefit, or complete onboarding, they won’t share it with people they know. Referral mechanics work best after the product creates a clear win.
The second pitfall is writing content that attracts the wrong audience. Broad finance content can bring traffic without signups. Build content around the exact money problem your product solves, then connect the article to a calculator, checklist, demo, or signup flow. Search traffic should lead to product education, not a dead end.
The third pitfall is treating compliance-related friction as only a legal or operations concern. It affects growth directly. If onboarding feels unexplained, users may abandon before they ever experience value. Clear explanations, progress indicators, and support access can protect conversion without weakening standards.
From 10,000 To 100,000 Users
Your first 10,000 users prove whether people care enough to sign up, activate, and share. The next stage is about repeatability. You identify the channels that brought activated users, then strengthen those loops with better onboarding, stronger education, better referral timing, deeper partner programs, and more precise positioning.
At this stage, segment your growth data. Don’t treat every user as the same. A student budgeting user, a freelancer banking user, and a small-business payments user may respond to different content, incentives, and partner channels. Organic growth becomes easier when your messaging matches the user’s financial job.
You can add paid channels later if the economics support it. Paid acquisition works better after your organic motion has revealed which audience converts, which value message resonates, and which onboarding path retains users. Until then, your fintech go-to-market strategy should focus on proof. Build trust, create value before signup, and give early users a reason to bring the next wave.
How To Get Your First 10,000 Fintech Users Without Paid Ads
- Build trust first
- Use referral waitlists
- Create money education content
- Partner with trusted channels
- Reduce onboarding friction
Turn Early Trust Into A Growth Engine
Your first 10,000 fintech users won’t come from one clever tactic. They come from a product people understand, trust, use, and feel safe recommending. Paid ads can wait until you know which audience activates and which message converts. Start with product-led growth, a referral-ready waitlist, useful financial content, partner distribution, and community feedback. When those pieces work together, your fintech go-to-market strategy becomes less dependent on budget and more dependent on the value users can repeat for you.
References
- TechCrunch: Revolut Hits 2 Million Users; Customer Acquisition Cost Is Still 0
- MarketingWeek: N26 Marketing Strategy
- Fincog: Digital Banking User Acquisition Channels
- First Round Review: The Waitlist Strategy
- HubSpot: Fintech Content Marketing
- AppsFlyer: Performance Index Finance Edition
- Monzo: Golden Tickets
- CB Insights: Fintech Startup Challenges
- Forbes Finance Council: Building A Fintech Community That Drives Organic Growth
- FinTech Magazine: Neobank Growth Strategies Without Paid Ads
- Andreessen Horowitz: The Fintech Organic Growth Playbook